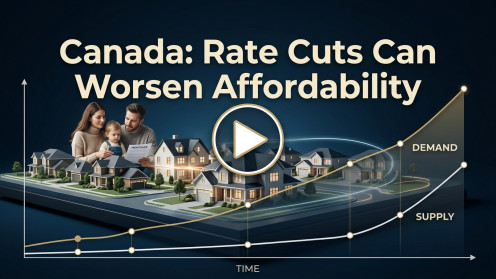
When the Bank of Canada cuts interest rates, it’s easy to assume that lower borrowing costs will make homeownership more accessible. But research from central bank economists tells a more complex story. In Canada, we typically see an uptick in home resales soon after a rate cut, with the strongest impact showing up 18 to 24 months later. However, the supply side—meaning new housing starts—lags behind, often beginning to increase only about two years after the rate cut. Strong job markets can intensify this demand, as buyers feel more confident and lending is easier, pushing activity even higher. Yet for builders, it takes time to respond: higher prices and improved financing make new projects more attractive, but planning and permitting, especially for multi-unit developments, add further delays. Ultimately, while rate cuts may eventually lead to more housing supply, demand always moves first. As a Realtor and Broker with nearly two decades of experience in the GTA, I’ve seen how affordability challenges can’t be solved by monetary policy alone—timing and market dynamics matter just as much.
Leave a Reply